
From Code to Orbit: The Structural Case for India's Deeptech Pivot
Introduction
For much of the past two decades, India's contribution to the global technology economy was defined by software services and consumer internet platforms, which is a model that built enormous wealth and made the country the world's third-largest startup ecosystem.
That story is changing. More than ever before, the best received pitches in Bengaluru, Hyderabad, and Chennai are for rocket propulsion, semiconductor design, and autonomous hardware, not apps. And this isn't just a style choice of what gets funded. It's the real concentration of money, people, and political support around "deep tech" ventures based on frontier science and engineering breakthroughs as opposed to incremental software work.
The Data Behind the Narrative
The scale of this shift is now visible in hard numbers. In fact, Indian deeptech companies cumulatively raised $11.4 billion in funding between 2015 and mid-2026, according to the Bharat Deep Tech Report 2026 published by the Indian Venture and Alternate Capital Association (IVCA). 2025 was a record year for Indian deeptech firms, which saw a total raise of $2.96 billion across 189 deals, despite a slowdown in funding in the Indian startup ecosystem overall. Analytically speaking, here is what that reveals: investors haven't just raised the tide with the roadmap; they have explicitly taken a far-flung sector-specific decision to reallocate the capital and instead pursue science-and-engineering-led startups, even when pulling back elsewhere.
That very same report further pointed out that over 85% of all the deeptech funding raised in India since 2015 was obtained in the last six years, suggesting that the sector has only very recently come of age and matured from doing mostly early proof-of-concept experiments to delivering products that have undergone verifiable commercialisation. Of all the capital, funding and deals raised, AI and generative AI, followed by electric vehicles and battery technology, were the highest in terms of both dollars and the number of deals, while semiconductors and space tech were identified as the fastest-growing industrial segments and areas of research, consistent with India's national aspirations around technological self-sufficiency. When it comes to the distribution of deals and funding across India, the report found that Bengaluru on its own accounts for nearly 50%, with the rest of the country grabbing less than half.
Space as the Sector's Proof Point
If any single industry illustrates the credibility of India's hardware pivot, it is private space. Skyroot Aerospace's trajectory offers a useful case study. In May 2026, the Hyderabad-based launch vehicle company raised approximately $60 million in a round co-led by Sherpalo Ventures and GIC, with participation from BlackRock-managed funds, Arkam Ventures, and the Shanghvi Family Office, pushing its valuation to $1.1 billion and making it India's first space-tech unicorn. The round is notable not just for its size but for its composition: sovereign wealth capital (GIC) and global asset managers (BlackRock) backing a hardware company whose Vikram-1 rocket is roughly 95% indigenously built and expected to draw significant demand from the global telecommunications sector, with around 90% of Skyroot's customers based outside India. That the company's valuation nearly doubled in about thirty months also suggests investors are pricing in execution risk more favourably than in earlier cycles, when Indian hardware ventures were often viewed as uninvestable relative to their software counterparts.
This is not the only data point. Alongside Skyroot, companies including Agnikul Cosmos, Dhruva Space, Pixxel and Digantara are working on propulsion, satellite platforms and orbital-debris-tracking technology. Even if all of the Indian space startups do not go on to become businesses on the scale of ISRO, the existence of so many private-sector firms working on these goods and services shows the ecosystem in India is maturing. India's private space startup ecosystem lines up with broader sector reporting that India's private space startup ecosystem is approaching 440 companies as the private-sector push gathers speed through 2026.
Policy Architecture and Patient Capital
A defining characteristic of deeptech like the long R&D cycles, capital-heavy prototyping, and complex regulation makes deeptech firms structurally different from software startups, and Indian policymakers seem to be acknowledging as much. In April 2026, the government announced the Startup India Fund of Funds 2.0, creating a corpus of 10,000 crores to acquire commitments to Alternative Investment Funds, with a focus on deeptech, technology-focused manufacturing and early-growth-stage companies. The intention here, as was articulated, was to increase the supply of institutional capital for companies that diverge from software-investing norms. This complements the operational R & D and Innovation (RDI) Scheme and the India Semiconductor Mission, creating a multilayer public-capital framework for deeptech commercialisation.
Yet the same IVCA survey data complicates any triumphalist reading. Despite these schemes, 40% of surveyed venture funds reported having never engaged with any government capital vehicle, pointing to a persistent gap between policy design and on-the-ground fund utilisation. More critically, the survey identified a structural weak point in the financing pipeline: fund participation drops sharply at the Series B/C stage, with fewer investors able to write larger cheques to growth-stage companies.
Perhaps the single biggest limiting factor for the long term of deeptech in India. Spotting and encouraging deeptech entrepreneurs has definitely begun, but long-term success hinges on an ecosystem that can finance deeptech innovators through the critical scale-up phase – larger-ticket funds that many deeptech firms need to grow from a proof of concept into full-scale commercial products globally. Traditionally, Indian hardware startups have been quickly sold off or listed in foreign markets.
The exit environment reflects this immaturity. IVCA data shows 62% of funds cited exit visibility as their primary challenge, with secondary transactions accounting for 56% of all exits in the period studied, which is a signal that public-market exits (IPOs) remain the exception rather than the rule for deep-tech companies, unlike in India's more established software and fintech sectors.
An Analytical Assessment
Overall, the body of data confirms a measured yet real read on structural change rather than hype about cycles. How funding has focused on AI, semiconductors and spacetech; how some credible unicorns were born using homegrown hardware (like Skyroot); how policy and a fund-of-funds ecosystem were purposefully built – these all led, in Rajat Tandon's words, "from promise to more investible commitments, with an increasingly institutionalised ecosystem play".
However, three analytical caveats temper the enthusiasm. First, India's deep tech capital base, while growing rapidly in percentage terms, remains small in absolute terms relative to the United States and China, and much of it is still concentrated in early rounds rather than growth-stage financing. Second, geographic concentration in Bengaluru risks under-leveraging engineering talent elsewhere in the country. Third, and most consequentially, cross-border regulatory friction, export controls, dual-use technology restrictions, and the need for internationally recognised IP protection remains a binding constraint for hardware ventures seeking to scale beyond the domestic market, a challenge that policy alone cannot resolve.
Conclusion
India's transition from software exporter to deep-tech engineer is therefore real, measurable, and policy-supported, but it is a transition still in its early-to-middle innings, dependent on whether growth-stage capital and international market access can keep pace with early-stage enthusiasm and government intent.
Sources
- YourStory — Indian deeptech investments reach $11.4B: Report
- Outlook Business — India's Deeptech Funding Crosses $11 Bn As Investors Turn To AI, Semiconductors
- Business Standard — Over 85% of India's deeptech funding raised in past six years: IVCA
- The Week — Skyroot Aerospace becomes India's first space tech unicorn
- Outlook Business — Skyroot Aerospace Reaches Unicorn Orbit as Vikram-1 Launch Countdown Begins
- SatelliteToday — Skyroot Secures $60M in Funding, Becoming India's First Space 'Unicorn'
- Convergence Now — India's Startup Funding Map: AI, Sustainability & Deeptech Leading the Next Wave
- Seafund — DeepTech Startups in India: Funding & Innovation 2026
- YourStory (original reference article) — From software to satellites: Why India's next venture opportunity lies in deeptech

Related Blogs
Executive Summary
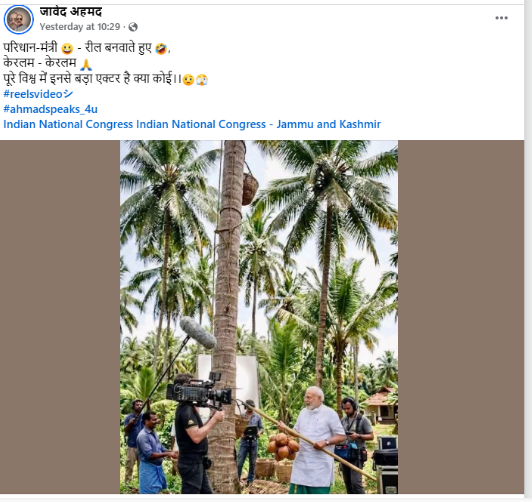
As Kerala gears up for its upcoming Assembly elections, political activity has intensified across the state. Amid this charged atmosphere, a purported image of Narendra Modi has gone viral on social media. The image shows the Prime Minister holding coconuts, with several photographers around him. It is being claimed that the photo was taken during his recent visit for the 2026 Kerala Assembly election campaign.
However, an research by the CyberPeace has debunked the claim, confirming that the image is fake and generated using artificial intelligence.
Claim
A Facebook user named “Javed Ahmad” shared the viral image on April 6, 2026, with a sarcastic caption suggesting that the Prime Minister was posing for reels during his Kerala visit.
- https://www.facebook.com/Ahmadspeaks4u/posts/pfbid0aRnhwXBjnfSXF9S48vaH1gTQrGQmxnRmhpJCRxMWazqLJhYs6zxM9rot51qtBgRLl
- https://perma.cc/N3AM-Q2YC
Fact Check
To verify the claim, we conducted keyword searches on Google but found no credible news reports supporting it. A reverse image search also did not yield any reliable sources. Additionally, a thorough review of the Prime Minister’s official social media accounts showed no trace of such an image or event. Given these inconsistencies, suspicion arose about the image’s authenticity.
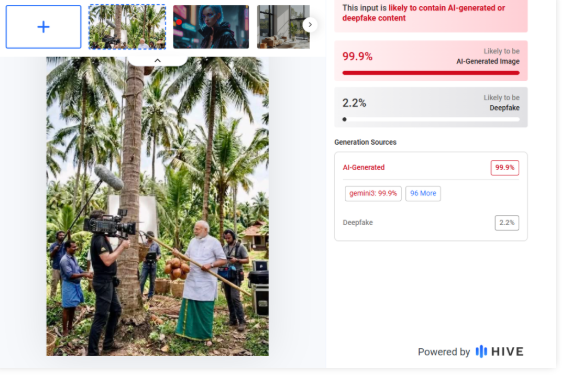
The viral image was then analyzed using AI detection tools. Results from HIVE Moderation indicated a 99% probability that the image is AI-generated.
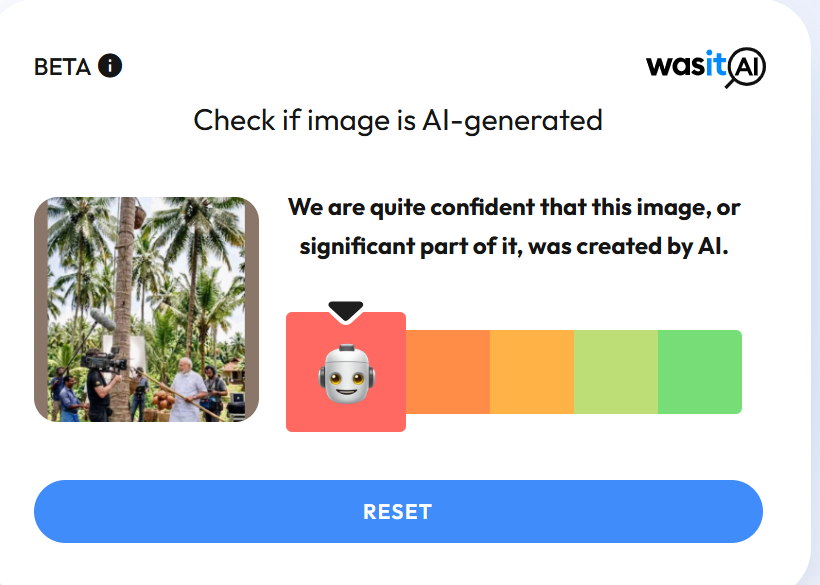
Another tool, Wasit AI, also confirmed that the image is artificially created.
Conclusion
The claim is false. The viral image of Prime Minister Narendra Modi is not real and has been generated using AI tools, likely similar to Google AI.

Introduction
Over the past few years, the virtual space has been an irreplaceable livelihood platform for content creators and influencers, particularly on major social media platforms like YouTube and Instagram. Yet, if this growth in digital entrepreneurship is accompanied by anything, it is a worrying trend, a steep surge in account takeover (ATO) attacks against these actors. In recent years, cybercriminals have stepped up the quantity and level of sophistication of such attacks, hacking into accounts, jeopardising the follower base, and incurring economic and reputational damage. They don’t just take over accounts to cause disruption. Instead, they use these hijacked accounts to run scams like fake livestreams and cryptocurrency fraud, spreading them by pretending to be the original account owner. This type of cybercrime is no longer a nuisance; it now poses a serious threat to the creator economy, digital trust, and the wider social media ecosystem.
Why Are Content Creators Prime Targets?
Content creators hold a special place on the web. They are prominent users who live for visibility, public confidence, and ongoing interaction with their followers. Their social media footprint tends to extend across several interrelated platforms, e.g., YouTube, Instagram, X (formerly Twitter), with many of these accounts having similar login credentials or being managed from the same email accounts. This interconnectivity of their online presence crosses multiple platforms and benefits workflow, but makes them appealing targets for hackers. One entry point can give access to a whole chain of vulnerabilities. Attackers, once they control an account, can wield its influence and reach to share scams, lead followers to phishing sites, or spread malware, all from the cover of a trusted name.
Popular Tactics Used by Attackers
- Malicious Livestream Takeovers and Rebranding - Cybercriminals hijack high-subscriber channels and rebrand them to mimic official channels. Original videos are hidden or deleted, replaced with scammy streams using deep fake personas to promote crypto schemes.
- Fake Sponsorship Offers - Creators receive emails from supposed sponsors that contain malware-infected attachments or malicious download links, leading to credential theft.
- Malvertising Campaigns - These involve fake ads on social platforms promoting exclusive software like AI tools or unreleased games. Victims download malware that searches for stored login credentials.
- Phishing and Social Engineering on Instagram - Hackers impersonate Meta support teams via DMs and emails. They direct creators to login pages that are cloned versions of Instagram's site. Others pose as fans to request phone numbers and trick victims into revealing password reset codes.
- Timely Exploits and Event Hijacking - During major public or official events, attackers often escalate their activity. Hijacked accounts are used to promote fake giveaways or exclusive live streams, luring users to malicious websites designed to steal personal information or financial data.
Real-World Impact and Case Examples
The reach and potency of account takeover attacks upon content creators are far-reaching and profound. In a report presented in 2024 by Bitdefender, over 9,000 malicious live streams were seen on YouTube during a year, with many having been streamed from hijacked creator accounts and reassigned to advertise scams and fake content. Perhaps the most high-profile incident was a channel with more than 28 million subscribers and 12.4 billion total views, which was totally taken over and utilised for a crypto fraud scheme live streaming. Additionally, Bitdefender research indicated that over 350 scam domains were utilised by cybercriminals, directly connected via hijacked social media accounts, to entice followers into phishing scams and bogus investment opportunities. Many of these pieces of content included AI-created deep fakes impersonating recognisable personalities like Elon Musk and other public figures, providing the illusion of authenticity around fake endorsements (CCN, 2024). Further, attackers have exploited popular digital events such as esports events, such as Counter-Strike 2 (CS2), by hijacking YouTube gaming channels and livestreaming false giveaways or referring viewers to imitated betting sites.
Protective Measures for Creators
- Enable Multi-Factor Authentication (MFA)
Adds an essential layer of defence. Even if a password is compromised, attackers can't log in without the second factor. Prefer app-based or hardware token authentication.
- Scrutinize Sponsorships
Verify sender domains and avoid opening suspicious attachments. Use sandbox environments to test files. In case of doubt, verify collaboration opportunities through official company sources or verified contacts.
- Monitor Account Activity
Keep tabs on login history, new uploads, and connected apps. Configure alerts for suspicious login attempts or spikes in activity to detect breaches early. Configure alerts for suspicious login attempts or spikes in activity to detect breaches early.
- Educate Your Team
If your account is managed by editors or third parties, train them on common phishing and malware tactics. Employ regular refresher sessions and send mock phishing tests to reinforce awareness.
- Use Purpose-Built Security Tools
Specialised security solutions offer features like account monitoring, scam detection, guided recovery, and protection for team members. These tools can also help identify suspicious activity early and support a quick response to potential threats.
Conclusion
Account takeover attacks are no longer random events, they're systemic risks that compromise the financial well-being and personal safety of creators all over the world. As cybercriminals grow increasingly sophisticated and realistic in their scams, the only solution is a security-first approach. This encompasses a mix of technical controls, platform-level collaboration, education, and investment in creator-centric cybersecurity technologies. In today's fast-paced digital landscape, creators not only need to think about content but also about defending their digital identity. As digital platforms continue to grow, so do the threats targeting creators. However, with the right awareness, tools, and safeguards in place, a secure and thriving digital environment for creators is entirely achievable.
References
- https://www.bitdefender.com/en-au/blog/hotforsecurity/account-takeover-attacks-on-social-media-a-rising-threat-for-content-creators-and-influencers
- https://www.arkoselabs.com/account-takeover/social-media-account-takeover/
- https://www.imperva.com/learn/application-security/account-takeover-ato/
- https://www.security.org/digital-safety/account-takeover-annual-report/
- https://www.niceactimize.com/glossary/account-takeover/

Introduction
MSMEs, being the cornerstone of the Indian economy, are one of the most vulnerable targets in cyberspace and no enterprise is too small to be a target for malicious actors. MSMEs hardly ever perform a cyber-risk assessment, but when they do, they may run into a number of internal problems, such as cyberattacks brought on by inadequate networking security, online fraud, ransomware assaults, etc. Tackling cyber threats in MSMEs is critical mainly because of their high level of dependance on digital technologies and the growing sophistication of cyber attacks. Protecting them from cyber threats is essential, as a security breach can have devastating consequences, including financial loss, reputational damage, and operational disruptions.
Key Cyber Threats that MSMEs are facing
MSMEs are most vulnerable to are phishing attacks, ransomware, malware and viruses, insider threats, social engineering attacks, supply chain attacks, credential stuffing and brute force attacks and Distributed Denial of Service (DDoS) Attacks. Some of these attacks are described as under-
- Insider threats arise from employees or contractors who intentionally or unintentionally compromise security. It involves data theft, misuse of access privileges, or accidental data exposure.
- Social engineering attacks involve manipulating individuals into divulging confidential information or performing actions that compromise security by pretexting, baiting, and impersonation.
- Supply chain attacks exploit the trust in relationships between businesses and their suppliers and introduce malware, compromise data integrity, and disrupt operations.
- Credential stuffing and brute force attacks give unauthorized access to accounts and systems, leading to data breaches and financial losses.
Challenges Faced by MSMEs in Cybersecurity
The challenges faced by MSMEs in cyber security are mainly due to limited resources and budget constraints which leads to other issues such as a lack of specialized expertise as MSMEs often lack the IT support of cyber security experts. Awareness and training are needed to mitigate poor understanding of cyber threats and their complexity in nature. Vulnerabilities in the supply chain are present as they rely on third-party vendors and partners often, introducing potential supply chain vulnerabilities. Regulatory compliance is often complex and is taken seriously only when an issue crops up but it needs special attention especially with the DPDP Act coming in. The lack of an incident response plan leads to delayed and inadequate responses to cyber incidents, increasing the impact of breaches.
Best Practices for Tackling Cyber Threats for MSMEs
To effectively tackle cyber threats, MSMEs should adopt a comprehensive approach such as:
- Implementing and enforcing strong access controls by using MFA or 2FA and password policies. Limiting employee access as role based and updating the same as and when needed.
- Regularly apply security patches and use automated patch management solutions to prevent exploitation of known vulnerabilities.
- Conduct employee training and awareness programs and promote a security-first approach for the employees and assessing employee readiness to identify improvement areas.
- Implement network security measures by using firewalls and intrusion detection systems. Using secure Wi-Fi networks via strong encryptions and changing default credentials for the router are recommended, as is segmenting networks to limit lateral movement within the network in case of a breach.
- Regular data backup ensures that in case of an attack, data loss can be recovered and made available in secure offsite locations to protect it from unauthorized access.
- Developing an incident response plan that outlines the roles, responsibilities and procedure for responding to cyber incidents with regular drills to ensure readiness and clear communication protocols for incident reporting to regulators, stakeholders and customers.
- Implement endpoint security solutions using antivirus and anti-malware softwares. Devices should be against unauthorized access and implement mobile device management solutions enforcing security policies on employee-owned devices used for work purposes.
- Cyber insurance coverage will help in transferring financial risks in case of cyber incidents. It should have comprehensive coverage including business interruptions, data restoration, legal liabilities and incident response costs.
Recommended Cybersecurity Solutions Tailored for MSMEs
- A Managed Security Service Provider offers outsourced cybersecurity services, including threat monitoring, incident response, and vulnerability management that may be lacking in-house.
- Cloud-Based Security Solutions such as firewall as a service and Security Information and Event Management , provide scalable and cost-effective protection for MSMEs.
- Endpoint Detection and Response (EDR) Tools detect and respond to threats on endpoints, providing real-time visibility into potential threats and automating incident response actions.
- Security Awareness Training Platforms deliver interactive training sessions and simulations to educate employees about cybersecurity threats and best practices.
Conclusion
Addressing cyber threats in MSMEs requires a proactive and multi-layered approach that encompasses technical solutions, employee training, and strategic planning. By implementing best practices and leveraging cybersecurity solutions tailored to their specific needs, MSMEs can significantly enhance their resilience against cyber threats. As cyber threats continue to evolve, staying informed about the latest trends and adopting a culture of security awareness will be essential for MSMEs to protect their assets, reputation, and bottom line.
References:
- https://economictimes.indiatimes.com/small-biz/security-tech/security/cyber-security-pitfalls-and-how-negligence-can-be-expensive-for-msmes/articleshow/99508822.cms?from=mdr
- https://www.investopedia.com/financial-edge/0112/3-ways-cyber-crime-impacts-business.aspx
- https://www.financialexpress.com/business/sme-msme-tech-cisco-launches-new-tool-for-smbs-to-assess-their-cybersecurity-readiness-2538348/
- https://www.cloverinfotech.com/blog/small-businesses-big-problems-are-cyber-attacks-crushing-indias-msmes/
