
#FactCheck - "AI-Generated Image of UK Police Officers Bowing to Muslims Goes Viral”
Executive Summary:
A viral picture on social media showing UK police officers bowing to a group of social media leads to debates and discussions. The investigation by CyberPeace Research team found that the image is AI generated. The viral claim is false and misleading.

Claims:
A viral image on social media depicting that UK police officers bowing to a group of Muslim people on the street.


Fact Check:
The reverse image search was conducted on the viral image. It did not lead to any credible news resource or original posts that acknowledged the authenticity of the image. In the image analysis, we have found the number of anomalies that are usually found in AI generated images such as the uniform and facial expressions of the police officers image. The other anomalies such as the shadows and reflections on the officers' uniforms did not match the lighting of the scene and the facial features of the individuals in the image appeared unnaturally smooth and lacked the detail expected in real photographs.

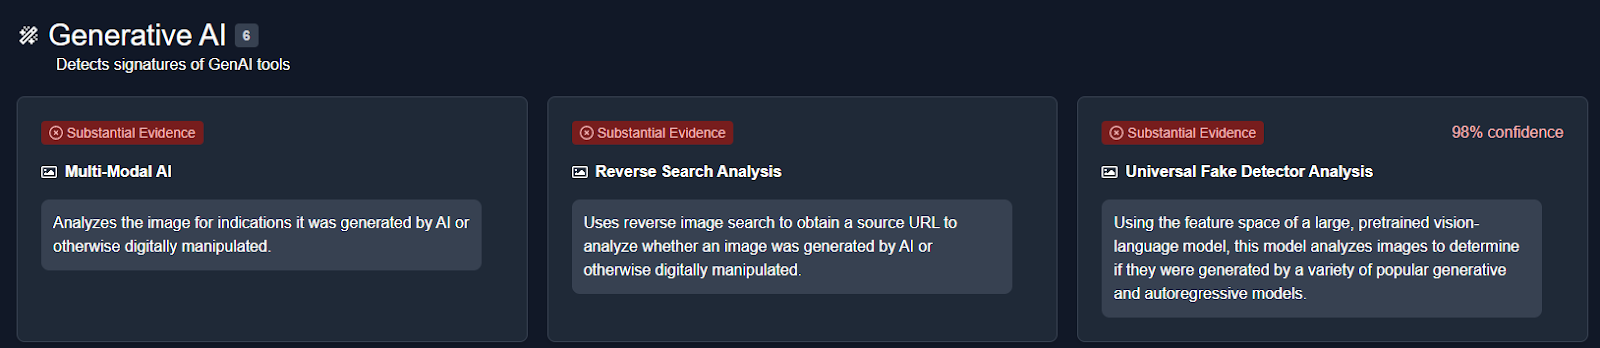
We then analysed the image using an AI detection tool named True Media. The tools indicated that the image was highly likely to have been generated by AI.


We also checked official UK police channels and news outlets for any records or reports of such an event. No credible sources reported or documented any instance of UK police officers bowing to a group of Muslims, further confirming that the image is not based on a real event.
Conclusion:
The viral image of UK police officers bowing to a group of Muslims is AI-generated. CyberPeace Research Team confirms that the picture was artificially created, and the viral claim is misleading and false.
- Claim: UK police officers were photographed bowing to a group of Muslims.
- Claimed on: X, Website
- Fact Check: Fake & Misleading

Related Blogs

The rapid innovation of technology and its resultant proliferation in India has integrated businesses that market technology-based products with commerce. Consumer habits have now shifted from traditional to technology-based products, with many consumers opting for smart devices, online transactions and online services. This migration has increased potential data breaches, product defects, misleading advertisements and unfair trade practices.
The need to regulate technology-based commercial industry is seen in the backdrop of various threats that technologies pose, particularly to data. Most devices track consumer behaviour without the authorisation of the consumer. Additionally, products are often defunct or complex to use and the configuration process may prove to be lengthy with a vague warranty.
It is noted that consumers also face difficulties in the technology service sector, even while attempting to purchase a product. These include vendor lock-ins (whereby a consumer finds it difficult to migrate from one vendor to another), dark patterns (deceptive strategies and design practices that mislead users and violate consumer rights), ethical concerns etc.
Against this backdrop, consumer laws are now playing catch up to adequately cater to new consumer rights that come with technology. Consumer laws now have to evolve to become complimentary with other laws and legislation that govern and safeguard individual rights. This includes emphasising compliance with data privacy regulations, creating rules for ancillary activities such as advertising standards and setting guidelines for both product and product seller/manufacturer.
The Legal Framework in India
Currently, Consumer Laws in India while not tech-targeted, are somewhat adequate; The Consumer Protection Act 2019 (“Act”) protects the rights of consumers in India. It places liability on manufacturers, sellers and service providers for any harm caused to a consumer by faulty/defective products. As a result, manufacturers and sellers of ‘Internet & technology-based products’ are brought under the ambit of this Act. The Consumer Protection Act 2019 may also be viewed in light of the Digital Personal Data Protection Act 2023, which mandates the security of the digital personal data of an individual. Envisioned provisions such as those pertaining to mandatory consent, purpose limitation, data minimization, mandatory security measures by organisations, data localisation, accountability and compliance by the DPDP Act can be applied to information generated by and for consumers.
Multiple regulatory authorities and departments have also tasked themselves to issue guidelines that imbibe the principle of caveat venditor. To this effect, the Networks & Technologies (NT) wing of the Department of Telecommunications (DoT) on 2 March 2023, issued the Advisory Guidelines to M2M/IoT stakeholders for securing consumer IoT (“Guidelines”) aiming for M2M/IoT (i.e. Machine to Machine/Internet of things) compliance with the safety and security standards and guidelines in order to protect the users and the networks that connect these devices. The comprehensive Guidelines suggest the removal of universal default passwords and usernames such as “admin” that come preprogrammed with new devices and mandate the password reset process to be done after user authentication. Web services associated with the product are required to use Multi-Factor Authentication and duty is cast on them to not expose any unnecessary user information prior to authentication. Further, M2M/IoT stakeholders are required to provide a public point of contact for reporting vulnerability and security issues. Such stakeholders must also ensure that the software components are updateable in a secure and timely manner. An end-of-life policy is to be published for end-point devices which states the assured duration for which a device will receive software updates.
The involvement of regulatory authorities depends on the nature of technology products; a single product or technical consumer threat may see multiple guidelines. The Advertising Standards Council of India (ASCI) notes that cryptocurrency and related products were considered as the most violative category to commit fraud. In an attempt to protect consumer safety, it introduced guidelines to regulate advertising and promotion of virtual digital assets (VDA) exchange and trading platforms and associated services as a necessary interim measure in February 2022. It mandates that all VDA ads must carry the stipulated disclaimer “Crypto products and NFTs are unregulated and can be highly risky. There may be no regulatory recourse for any loss from such transactions.” must be made in a prominent and unmissable manner.
Further, authorities such as Securities and Exchange Board of India (SEBI) and the Reserve Bank of India (RBI) also issue cautionary notes to consumers and investors against crypto trading and ancillary activities. Even bodies like Bureau of Indian Standards (BIS) act as a complimenting authority, since product quality, including electronic products, is emphasised by mandating compliance to prescribed standards.
It is worth noting that ASCI has proactively responded to new-age technology-induced threats to consumers by attempting to tackle “dark patterns” through its existing Code on Misleading Ads (“Code”), since it is applicable across media to include online advertising on websites and social media handles. It was noted by ASCI that 29% of advertisements were disguised ads by influencers, which is a form of dark pattern. Although the existing Code addressed some issues, a need was felt to encompass other dark patterns.
Perhaps in response, the Central Consumer Protection Authority in November 2023 released guidelines addressing “dark patterns” under the Consumer Protection Act 2019 (“Guidelines”). The Guidelines define dark patterns as deceptive strategies and design practices that mislead users and violate consumer rights. These may include creating false urgency, scarcity or popularity of a product, basket sneaking (whereby additional services are added automatically on purchase of a product or service), confirm shaming (it refers to statements such as “I will stay unsecured” when opting out of travel insurance on booking of transportation tickets), etc. The Guidelines also cater to several data privacy considerations; for example, they stipulate a bar on encouraging consumers from divulging more personal information while making purchases due to difficult language and complex settings of their privacy policies, thereby ensuring compliance of technology product sellers and e-commerce platforms/vendors with data privacy laws in India. It is to be noted that the Guidelines are applicable on all platforms that systematically offer goods and services in India, advertisers and sellers.
Conclusion
Consumer laws for technology-based products in India play a pivotal role in safeguarding the rights and interests of individuals in an era marked by rapid technological advancements. These legislative frameworks, spanning facets such as data protection, electronic transactions, and product liability, assume a pivotal role in establishing a regulatory equilibrium that addresses the nuanced challenges of the digital age. The dynamic evolution of the digital landscape necessitates an adaptive legal infrastructure that ensures ongoing consumer safeguarding amidst technological innovations. As the digital landscape evolves, it is imperative for regulatory frameworks to adapt, ensuring that consumers are protected from potential risks associated with emerging technologies. Striking a balance between innovation and consumer safety requires ongoing collaboration between policymakers, businesses, and consumers. By staying attuned to the evolving needs of the digital age, Indian consumer laws can provide a robust foundation for security and equitable relationships between consumers and technology-based products.
References:
- https://dot.gov.in/circulars/advisory-guidelines-m2miot-stakeholders-securing-consumer-iot
- https://www.mondaq.com/india/advertising-marketing--branding/1169236/asci-releases-guidelines-to-govern-ads-for-cryptocurrency
- https://www.ascionline.in/the-asci-code/#:~:text=Chapter%20I%20(4)%20of%20the,nor%20deceived%20by%20means%20of
- https://www.ascionline.in/wp-content/uploads/2022/11/dark-patterns.pdf

Introduction
In a groundbreaking move, India's Reserve Bank has embarked on a transformative journey with its Central Bank Digital Currency (CBDC) project. As the world grapples with the evolving landscape of digital finance, the implications of India's CBDC initiative extend beyond its borders, potentially reshaping global payment systems. The Union Minister of State for Finance, Shri Pankaj Chaudhary, revealed that on October 7, 2022, the Reserve Bank of India released a proposal note on Central Bank Digital Currency (CBDC). Two pilot projects using blockchain-based technology are described in the concept note: Digital Rupee-Wholesale (e₹-W) and Digital Rupee-Retail (e₹-R). Launched on November 1, 2022, the bulk trading pilot aims to increase intermediary competitiveness, particularly in the resolution of trades in the secondary market involving sovereign debt. In parallel, on December 1, 2022, the retail banking pilot, known as e₹-R, got underway in a limited user group with eight banks taking part in stages.
The digital asset known as e₳-R is issued across financial institutions for Person-to-Person (P2P) and Person-to-Merchant (P2M) transactions. It is intended to serve as a virtual currency that represents legal money and exhibits characteristics similar to actual cash. Based on input gathered during the continuing trial phases, the RBI intends to progressively broaden the pilot project's scope.
Central Bank Digital Currency Pilot Projects
Central Bank Digital Currency (CBDC), which the Central Bank of India is promoting, may easily perform an essential part in payments made across borders, according to Reserve Bank Governor Shaktikanta Das. The CBDC is going to be expanded to the international financial markets after being implemented as a trial in both the retail and wholesale industries.
CBDC in International Payments
He emphasized that although physical currency will still exist, the CBDC will eventually replace all forms of money worldwide.
"CBDC is going to be the future currency of the world and it is necessary that every central bank, every country works on CBDC," he stated. He also stated that as worldwide commerce moves more and more around science and technology, CBDCs will play a significant role since they can effectively and affordably speed up payment processing across different countries. Regarding India's foreign exchange reserves, the governor stated that the selection to increase the resources as a safety net and protection versus contagion possibilities was made consciously.
CBDCs' Place in the Transnational Economic Revolution
In certain economies worldwide, having a CBDC internationally accessible could lead to more replacements for foreign currencies rather than the home currencies, which could cause financial aggregates to become volatile and change the mix of instruments of exchange.
CBDC may have benefits related to first-mover savings of scale, and other consequences even in everyday circumstances. If nations with global currencies have established CBDCs, they could strengthen current advantages and disadvantages, including consequences, particularly in terms of revenue. In a similar vein, CBDC might alter the structure of international liquidity while safeguarding asset supply. Additionally, and particularly if imposed abruptly, CBDC may, in certain circumstances, result in significant capital movements and associated repercussions on the foreign exchange rate as well as additional asset prices. Furthermore, nations may encounter difficulties in getting ready for virtual currencies issued by central banks.
The worldwide and international scope of CBDCs accessible to immigrants may become particularly apparent in situations where there is a widespread flight safety concern. In these circumstances, converting a CBDC into a foreign currency would make it possible for capital markets to deleverage more quickly. The elimination of debt challenges could show up as tight finance constraints and abrupt swings in foreign exchange markets if CBDCS expedited its flight from uncertainty.
Deposits of Foreign Exchange and Self-Dependency
Reserve Bank Governor Shaktikanta Das stated "We must rely on ourselves. We must maintain our robust reserves. In order to achieve that goal, we have been amassing quite substantial reserves, and the outside world has come to feel quite confident that India would be able to fulfil its contractual responsibilities to the international community no matter what the obstacles,"
Involvement of RBI in the Currency Market
Given that the trading community was confident that the Reserve Bank of India would be capable of and able to fulfil its contractual responsibilities, the value of the Indian rupee did not decline as dramatically. The RBI governor stated that the RBI does participate in the economy, but that "our engagement operates in two ways," he would not hesitate to acknowledge this.
The Value of Macroeconomic and Budgetary Cooperation
According to RBI Governor Das, the RBI makes purchases and sales of dollars based on the direction in which the financial sector is trending. However, the RBI does not intend to set a certain level for the rupee because it does not consider any specific threshold for the Indian rupee's conversion rate against the US dollar. He also emphasized how crucial it is for both the financial and monetary authorities to work together.
Conclusion
India's CBDC project signals a transformative shift in the global digital finance landscape. Governor Shaktikanta Das envisions CBDCs as the future global currency, emphasizing their role in international payments. The potential impact on financial systems, cross-border transactions, and the need for self-reliance underscore the significance of India's CBDC initiative in shaping the evolving dynamics of the digital economy. As the project progresses, close cooperation between financial and monetary authorities becomes imperative for navigating the challenges and opportunities associated with this groundbreaking venture.
References
- https://economictimes.indiatimes.com/news/economy/policy/central-bank-digital-currency-can-play-important-role-in-cross-border-payment-rbi-guv/articleshow/104706717.cms
- https://www.bis.org/cpmi/publ/d174.pdf
- https://bfsi.economictimes.indiatimes.com/news/fintech/explained-how-rbi-is-leveraging-upi-to-push-the-use-of-retail-cbdc/103591989
- https://www.imf.org/en/News/Articles/2022/02/09/sp020922-the-future-of-money-gearing-up-for-central-bank-digital-currency
- https://www.business-standard.com/economy/news/cbdc-pilot-projects-show-promising-results-rbi-governor-shaktikanta-das-123102601171_1.html
Executive Summary
The Cockroach Janata Party had called for a protest on October 10, demanding the resignation of Chief Election Commissioner Gyanesh Kumar. Before the protest could take place, Delhi Police detained thousands of supporters. During the incident, several allegations of misconduct by Delhi Police personnel against women protesters and journalists also emerged. CyberPeace Research found that such allegations against Delhi Police had indeed been reported. However, this image is AI-generated.
Claim
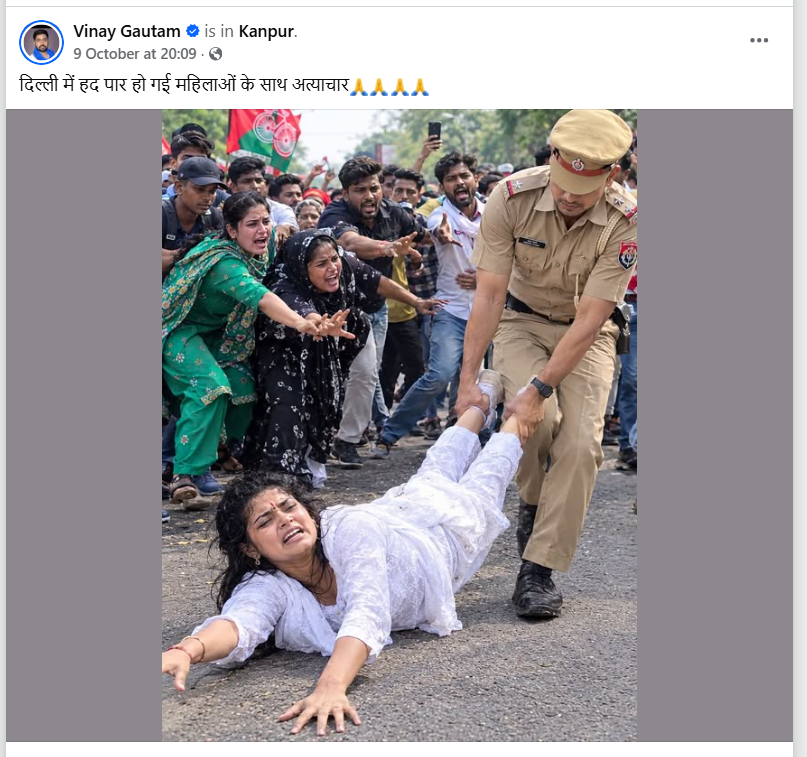
Some images are being shared on social media with the claim that Delhi Police personnel held and dragged women protesters in an inappropriate manner. The first image shows a police personnel dragging a woman by her legs. The caption reads, “Things have crossed all limits in Delhi. Atrocities against women.”
https://ghostarchive.org/archive/1LyAy
Fact Check
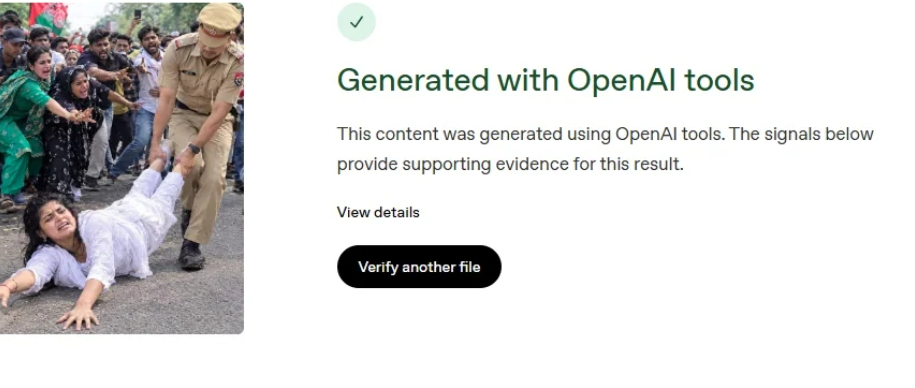
Upon closely examining the viral images, we found that the woman depicted in both photographs appears to be the same. However, it seems implausible that the woman’s clothing would change in the middle of a protest.We then examined both images using OpenAI’s verification tool. The tool clearly indicated that both photographs were generated using artificial intelligence (AI).
Conclusion
Our research found that such allegations against Delhi Police were indeed reported. However, the viral image is AI-generated.

